Move-Up Buyers
5 Costs Your Mortgage Calculator Skips
 Matt Robertshaw · NMLS #925153
What costs does a mortgage calculator leave out of your monthly payment?
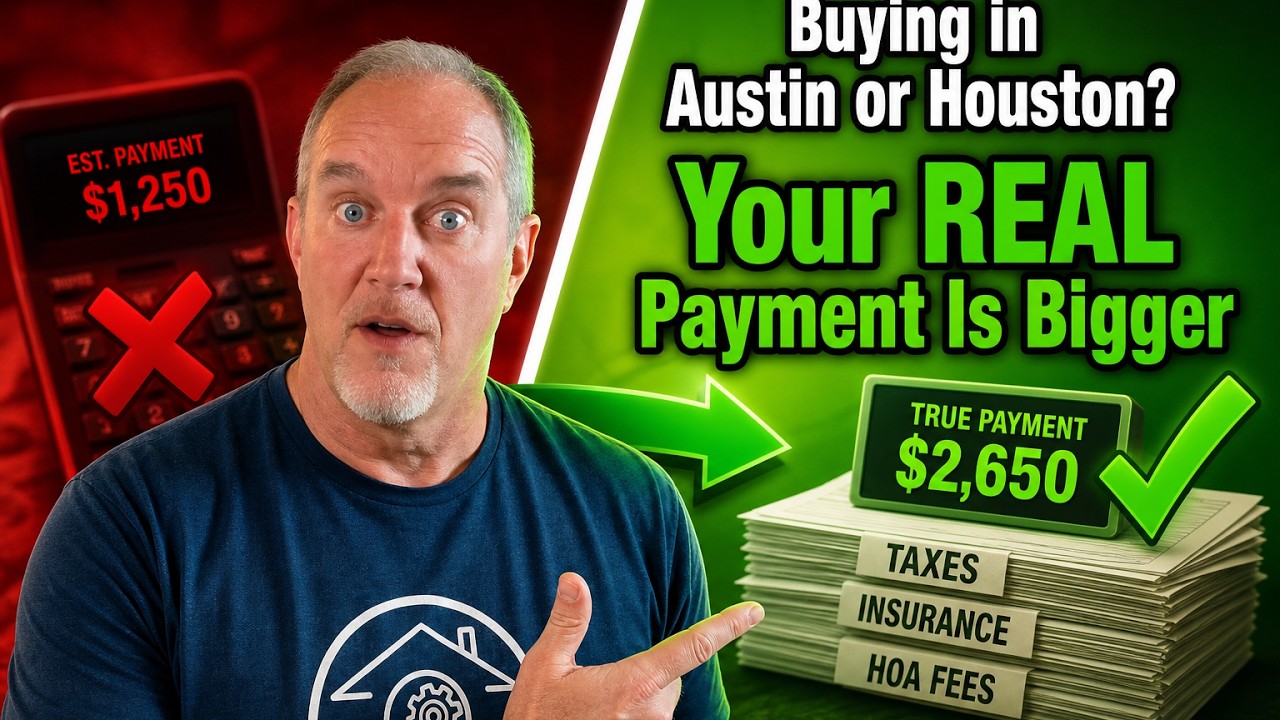
A basic mortgage calculator usually shows only principal and interest, which is the smallest version of your payment. Your real monthly cost is PITI: principal, interest, property taxes, and homeowners insurance. It also skips mortgage insurance if you put down less than 20 percent and HOA dues in many communities. In Texas, taxes and insurance make this gap especially large.
What costs does a mortgage calculator leave out?
A basic mortgage calculator usually shows only principal and interest, which is the smallest version of your payment that will ever exist. Your real monthly cost is PITI: principal, interest, property taxes, and homeowners insurance. It also skips mortgage insurance when you put down less than 20 percent and HOA dues in many communities. In Texas, taxes and insurance make this gap especially large.
You typed the price of the bigger house into a calculator, saw a number, and felt your stomach drop. But that number is not your payment. The real one is higher. If you are a growing family in Katy or Round Rock trying to give the kids their own rooms, that gap is exactly what has kept you frozen.
Why is the calculator number not your real payment?
A free calculator on Google, or the one your favorite finance personality points you to, mostly does one job. It takes your loan amount, your interest rate, and your term, and it returns principal and interest.
Principal is the chunk that pays down what you borrowed. Interest is what the lender charges you to borrow it. Add those together and you get a clean, calm little number. That number is real. It is just not your payment, because nobody lives in a house that only costs principal and interest.
The Consumer Financial Protection Bureau has warned that a mortgage calculator may be setting you up for a surprise when it leaves out taxes and insurance.
What does PITI mean?
The full payment has a name. We call it PITI. That stands for principal, interest, taxes, and insurance. Four parts, not two. The two parts most calculators skip, taxes and insurance, are the two that hit Texas families the hardest.
Property taxes
Texas has no state income tax, so the state leans on property taxes instead. They run high here compared to most of the country. On a bigger house, that bill scales up with the price. Move from a starter home to something with more room, more yard, and that better school zone, and the tax line does not just rise a little. It can jump by hundreds of dollars a month, and that lands inside your payment every single month whether you budgeted for it or not.
Homeowners insurance
If you have owned in Texas the last few years, you already feel this one. Storms, wind, hail, and rebuild costs have pushed premiums up hard, and every renewal seems to bring another increase. A bigger, pricier home means a bigger policy. That is the second cost the calculator quietly leaves out, and in this state it is not small.
Mortgage insurance
Here is a third cost that surprises people. If you put down less than 20 percent, most loans add mortgage insurance. That is a fee that protects the lender, not you, and it rides along in your payment until you have enough equity. The calculator does not know your down payment plan, so it usually ignores this entirely.
HOA dues
And the fourth, HOA dues. A lot of the newer master-planned communities around Houston and Austin come with a homeowners association, and those monthly or annual dues are real money that never touches a basic calculator.
How do you use a mortgage calculator the right way?
Here is the honest way to use one of these tools. Do this next time you are sitting there scaring yourself at midnight.
Do not stop at the number it gives you. Put in the price and your down payment, then go hunting for the property tax rate on that specific house and add it. Pull a real insurance estimate for that home, not a guess. Add HOA if the neighborhood has it. Add mortgage insurance if your down payment is under 20 percent. Now you are looking at PITI. Now you are looking at the truth.
Some tools do more of this for you. The Fannie Mae mortgage calculator prompts you to include taxes, insurance, and HOA so the estimate lands closer to reality.
Why does the calculator keep move-up buyers frozen?
When people add these costs, the number gets bigger and they feel worse. That is exactly why I do not want you making this decision off a calculator at all.
That tool only shows you one line of a much bigger equation. It shows the scary payment. It never shows you the strategy that changes the payment. It cannot see your real objective. It cannot see the car loan and the credit cards quietly eating your monthly cash flow. And it has no idea that a chunk of what you spend every month is feeding things that lose value instead of a home that gains it.
You are not stuck because of your rate. You are stuck because nobody has ever run the whole picture for you. Keep versus move, both mortgages, the taxes, the insurance, all of it in one honest view. Sometimes the answer is move now. Sometimes it is stay and pull from your equity instead. Sometimes it is not yet.
How do you find your actual number?
That is the whole reason I built the Redirect Roadmap. The first step is a self-assessment where you line up your current bills against what a new payment could actually look like, taxes and insurance included, so you can decide for yourself whether this is even worth a conversation. No pressure, no application, just your real numbers instead of a calculator's guess.
When we do talk, before anyone touches a loan file, we look at where your money is actually going each month. That moment, when a family sees how much is pointed at depreciating debt instead of an appreciating home, is usually when the bigger house stops feeling impossible.
If you want your actual number, not the calculator's number, that is a five-minute conversation, not a form to fill out.
Frequently asked questions
What does PITI stand for? +
PITI stands for principal, interest, taxes, and insurance. Principal is the part of your payment that reduces what you borrowed. Interest is what the lender charges to lend it. Taxes are your property taxes, and insurance is your homeowners policy. Most basic calculators only show the first two, principal and interest, which understates your real monthly cost. Adding taxes and insurance gives you the full PITI payment, which is the number you actually live with each month.
Why are Texas property taxes so high? +
Texas has no state income tax, so the state relies more heavily on property taxes to fund services. That means property tax rates here run higher than in most of the country. Because the tax is based on your home's value, moving up to a bigger or pricier house raises the tax line too, sometimes by hundreds of dollars a month. This cost is built into your monthly mortgage payment through an escrow account, so it affects affordability whether you budgeted for it or not.
When do you have to pay mortgage insurance? +
Most loans add mortgage insurance when you put down less than 20 percent. This fee protects the lender, not you, and it rides along inside your monthly payment until you build enough equity in the home. A basic mortgage calculator usually does not know your down payment plan, so it leaves this cost out entirely. If you plan to put down less than 20 percent, add an estimate for mortgage insurance to get a more accurate picture of your real payment.
Do mortgage calculators include HOA dues? +
No. Basic mortgage calculators almost never include homeowners association dues. Many newer master-planned communities around Houston and Austin come with an HOA, and those monthly or annual dues are real money that affects your budget. If the home you are considering sits in an HOA community, find the actual dues amount and add it to your calculation. Leaving it out can make a home look more affordable than it really is once you move in.
How can I estimate my true monthly mortgage payment? +
Start with the calculator, but do not stop at the number it gives you. Enter the price and your down payment for principal and interest, then add the specific property tax rate for that home, a real homeowners insurance quote, HOA dues if the neighborhood has them, and mortgage insurance if your down payment is under 20 percent. That total is your PITI, the payment you actually make each month. For a full keep-versus-move picture, a conversation with a mortgage professional runs all the numbers together.
Is my rate the reason I can't afford to move up? +
Often it is not the rate. Many move-up buyers stay frozen because nobody has run the whole picture for them: both mortgages, taxes, insurance, and where their money goes each month. A car loan or credit card debt can eat monthly cash flow that could support a bigger home. Sometimes the answer is to move now, sometimes to stay and pull from equity, and sometimes to wait. Seeing the full equation, not just a scary calculator number, is what makes the decision clear.
Sources
- Mortgage calculator — Fannie Mae
- Your mortgage calculator may be setting you up for a surprise — Consumer Financial Protection Bureau
About the author
Matt Robertshaw — Mortgage Strategist
NMLS #925153
With a passion for strategy and over two decades of experience in the residential mortgage industry, Matt saw a crucial need for a different approach. Our company's foundation lies in the belief that success stems from well-crafted strategies tailored to individual clients. As your trusted Mortgage Strategist, Matt utilizes his expertise and advanced tools to understand your unique financial objectives, both short and long term. By analyzing market trends, interest rates, and personalized factors, he formulates the most advantageous mortgage plans for home buyers and current homeowners alike. The Mortgage Strategists is committed to providing a seamless, personalized customer experience, bridging the gap between dreams and reality. Discover the power of strategy and unlock your path to financial success with The Mortgage Strategists.
Ready to talk numbers?
Schedule a 15-minute call. We'll walk through your situation and show you what's actually possible — no pressure, no pitch.
Book a call

